Daily Compound Interest: How It Really Works and Why It Matters
If you’ve spent any time researching investing, trading or building wealth, you’ll probably have come across the term daily compound interest.
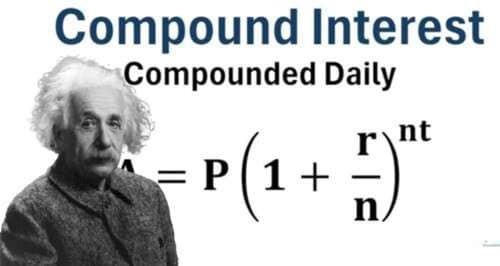
Compounding is one of those financial concepts that becomes much easier to understand once you see how it works. The basic idea is that your returns can potentially generate further returns when you leave them invested instead of withdrawing them.
In simple terms, you’re earning growth on growth.
However, there’s an important distinction to understand. Knowing how compound interest works mathematically is one thing. Expecting an investment to deliver the same return every day is something completely different.
In this article, I’ll explain daily compound interest, how the calculations work, why people find compounding interesting and what you should consider before believing the impressive figures you sometimes see online.
What is daily compound interest?
So, what exactly is daily compound interest?
Imagine starting with $1,000 and receiving a hypothetical return of 1% per day. Instead of withdrawing the gain, you leave it in your account so that the next calculation uses your increased balance.
After the first day, your balance would be $1,010.
If another 1% return were added the following day, you would earn $10.10 rather than $10 because the calculation would now be based on $1,010.
Your balance would increase to $1,020.10.
The process continues, with each new calculation using the updated balance.
That’s the basic principle behind daily compounding.
The difference might seem small at first, but over a longer period, the mathematical effect can become much more noticeable. The important point is that previous gains remain in the balance and contribute to future calculations.
How daily compounding returns work
When people discuss daily compounding returns, they’re generally referring to a process in which gains are added to a balance and then included in subsequent calculations.
Here’s a simple example.
You start with $1,000. A hypothetical 1% return gives you $10, increasing your balance to $1,010. The next 1% calculation is based on that new balance, producing another $10.10.
Your balance increases again, and that updated amount becomes the starting point for the next calculation.
The process looks like this:
Starting balance → return → new balance → further return → increased balance.
Of course, real investments don’t necessarily follow this pattern. A calculator can assume a fixed daily return, but financial markets are unpredictable. Returns can vary from day to day, and losses are possible.
That distinction matters, particularly if you’re researching trading strategies or investment opportunities that advertise consistent daily gains.
The 1% daily compound interest example
One calculation that frequently appears online involves 1% daily compound interest.
Let’s use a starting balance of $1,000 to see how the figures develop over the first three days.
| Day | Hypothetical daily return | Ending balance |
|---|---|---|
| Starting balance | N/A | $1,000.00 |
| Day 1 | $10.00 | $1,010.00 |
| Day 2 | $10.10 | $1,020.10 |
| Day 3 | $10.30 | $1,030.30 |
Notice that the percentage stays the same, but the dollar amount increases because the balance is getting larger.
This is what makes compounding interesting.
If you extend the calculation over weeks, months or years, the difference can become substantial. You can explore the mathematics using my free compound interest calculator.
However, I wouldn’t interpret these figures as evidence that earning 1% every day is realistic. The example assumes a constant positive return, with every gain reinvested and no losses, withdrawals, fees or other costs.
That is a mathematical assumption, not a promise of investment performance.
Why use a compound interest calculator?
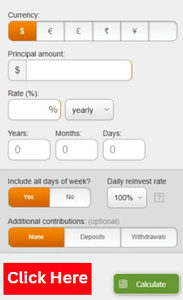
A compound interest calculator is a useful way to explore different scenarios without working through every calculation manually.
You can enter a starting balance, choose a hypothetical rate of return and change the length of time over which the balance compounds. Depending on the calculator, you may also be able to include regular contributions or compare different compounding frequencies.
I think the most useful approach is to experiment with the assumptions rather than simply looking for the biggest final number.
Try reducing the return. Increase the time period. Compare daily compounding with monthly or annual compounding. You could even start with a smaller amount to see how the figures change.
You’ll quickly discover that the final result depends heavily on the assumptions you enter.
This is also a good way to understand why some online investment projections look so impressive. A small change in the assumed return can make a considerable difference when repeated over a long period.
Just remember that a calculator demonstrates what could happen under particular conditions. It cannot establish what a real investment will deliver.
What does compound interest investment mean?
You’ll often encounter the phrase compound interest investment when researching ways to grow your money.
The principle is straightforward. If an investment generates a return and you leave that gain invested, your balance may increase. If further positive returns follow, they can potentially be earned on the larger balance.
Depending on the investment, this may happen through reinvested interest, dividends or other gains. The precise process depends on how the investment works.
However, I would always look beyond the projected final balance when researching an opportunity.
Ask yourself where the returns are supposed to come from. What risks are involved? Can the investment lose value? Are there fees, restrictions or withdrawal conditions? What happens if the market moves against you?
These questions are just as important as the potential upside.
A compound interest projection might show an attractive result, but it cannot tell you whether the investment is suitable, whether the assumptions are realistic or whether you could lose some or all of your money.
How does daily compounding work compared with simple interest?
The difference between simple interest and compound interest is easier to understand when you compare the calculations.
With simple interest, the return is generally calculated against the original principal. With compound interest, previously accumulated interest becomes part of the balance used for subsequent calculations.
For example, imagine starting with $1,000 and receiving a hypothetical 1% daily return.
With simple interest, the daily calculation remains $10 because it is always based on the original $1,000.
With daily compounding, the first $10 is added to the balance. The next calculation is therefore based on $1,010, producing $10.10. The following calculation uses the updated balance again.
Over time, this creates a difference between the two methods.
The effect depends on the rate, the length of time and whether the gains remain invested. In real financial products, the advertised interest rate and the method used to calculate and credit interest also matter.
Daily compound interest calculator
If you want to explore the figures yourself, you can use the Daily Compound Interest Calculator.
View the calculator and experiment with different figures.
Try different starting balances, rates and time periods to see how the results change. If the calculator supports different compounding frequencies, compare those as well.
For a more realistic illustration, remember to account for fees, taxes where applicable, withdrawals and the possibility of negative returns. A calculation that assumes uninterrupted growth will not reflect every aspect of an actual investment.
Why does compounding matter?
For me, the most interesting lesson isn’t about chasing a particular daily percentage. It’s about understanding what can happen when gains remain invested and contribute to future growth.
Over time, compounding can make a meaningful difference, which is one reason people often discuss the benefits of starting early and allowing investments more time to grow.
However, the outcome depends on the investment and its actual performance. A savings account paying interest under agreed terms is very different from a volatile trading strategy that may produce both gains and losses.
It’s important not to treat them as interchangeable.
You might see online examples showing how a relatively small starting amount could theoretically grow into a substantial sum. The arithmetic may be correct, but the assumptions behind the calculation deserve just as much attention.
A projection based on consistent positive returns is not a reliable forecast of what will happen in the real world.
Compounding can work both ways
There is another side to compounding that deserves attention.
People naturally focus on the potential benefits of positive returns, but investment losses can also have a significant effect on your balance.
For example, if an investment loses 20% of its value, a subsequent gain of 20% will not restore it to its original value. A $1,000 investment that falls by 20% becomes $800. A 20% gain on that reduced balance brings it to $960.
You would still be $40 below your starting amount.
This demonstrates why protecting your capital and understanding risk are important parts of any investment decision.
Understanding investment risk is just as important as understanding potential returns. An attractive growth calculation doesn’t remove the possibility of losses.
Don’t believe every compound interest projection
When researching daily compound interest, you’ll probably encounter impressive charts and examples showing what might happen if an investment earned a fixed percentage every day.
It’s worth approaching these claims carefully.
A calculator can demonstrate what happens if you assume a 1% daily return over a specified period. It does not prove that a particular investment can deliver that return consistently.
Markets fluctuate, trading involves risk, and investments can fall in value. Some opportunities also carry additional risks relating to the provider, liquidity, fees or the way returns are generated.
Before putting money into anything, research the underlying investment and understand how it works.
Be particularly cautious when somebody presents exceptionally high or consistent returns as guaranteed. Ask for verifiable information, consider what could go wrong and avoid making decisions based solely on projected profits.
I believe compound interest calculators are most useful as educational tools. They help you understand the mathematics, compare scenarios and question the assumptions behind financial claims.
Try different compound interest calculations yourself
If you want to understand compounding properly, spend a little time experimenting with different figures.
Start with a hypothetical balance and try several rates of return. Change the number of days or years and compare daily, monthly and annual compounding.
Then reduce the assumed return and see how much difference it makes. If the calculator allows regular contributions, explore how adding money over time changes the result.
This hands-on approach can be far more useful than simply looking at an impressive projection online.
You’ll also develop a better understanding of the difference between a theoretical calculation and a realistic financial expectation.
Albert Einstein and the eighth wonder of the world
You may have heard the saying that compound interest is the eighth wonder of the world, often attributed to Albert Einstein.
Although the attribution is disputed, the phrase is commonly used to illustrate the potential power of compounding.
The underlying idea is straightforward: when returns are reinvested, they can contribute to further growth. Given enough time and favourable returns, that process can have a significant effect on the balance.
However, the quote shouldn’t be taken as investment advice or as evidence that compounding will always produce positive results. The outcome still depends on the underlying investment, the returns achieved and the risks involved.
My final thoughts
Daily compound interest is a straightforward concept once you understand the calculation. You start with a balance, add a return, and use the updated balance for the next calculation. When gains remain invested, this can create the effect known as growth on growth.
The important thing is to understand what the numbers actually mean.
A calculator can show you what might happen under a particular set of assumptions, but it cannot tell you what an investment will deliver. Consistent daily returns should never be assumed simply because a spreadsheet or online calculator makes them look possible.
Use compound interest calculations to improve your understanding, compare hypothetical scenarios and learn why reinvesting gains can matter over time.
But always research the investment itself, understand the risks and consider whether it fits your financial circumstances before committing any money.
Remember, never invest money you cannot afford to lose, and never confuse a mathematical projection with a guaranteed return.
Disclaimer
The information in this article is provided for general educational and informational purposes only. It does not constitute financial, investment, trading, tax or legal advice. All examples involving compound interest, daily returns or investment growth are hypothetical illustrations and do not represent guarantees, predictions or promises of future performance. Investments and trading involve risk, returns can vary, and you may lose some or all of your invested capital. Conduct your own independent research and consider seeking advice from an appropriately qualified financial professional before making investment decisions. Never invest more than you can afford to lose.
Social Share